The surprising part of being the family bank is that the requests are rarely the tell. The tell is the structure around them: when the contact comes, what gets assumed about your money, how fast a no turns into a fight, and what you are asked to keep quiet. A text that opens with "$450 due Friday" and account digits, then "how are you," from a relative who has not called in weeks, tells you more than the figure does.
One transfer is help. Six transfers with the same script, the same timing, and the same silence when you need something back is a role you have been given and keep accepting.
The amount and the emergency, looked at alone, prove very little. The repeated shape is what proves it: contact that tracks a bill, framing that treats your income as shared, secrecy around a loan, repayment that waits because you can.
"Bank" is a role assigned by pattern. A single crisis can mimic it, and guilt can too, so the evidence is repetition, not one request. By the end you will be able to name the pattern, separate a true one-off from a sign that recurs, and test the least arguable sign you have with one small boundary and one sentence.
Quick Tips Before You Start
Log three months
Write down every date a relative asked for money and what it was for.
Save the messages
Screenshot asks as they arrive instead of trusting your memory of them.
Pull one bank statement
Highlight every outgoing transfer to family in a single month.
Count the no-asks
Notice how many calls in that same period had nothing to do with money.
Say less first
When asked for a figure, reply that you need a day to check your budget.
How the Ask Arrives
Before you judge the relationship, judge the timing. When a request shows up is often more revealing than what it asks for, because timing is harder to fake than warmth.
The signs in this stretch are the ones you can prove with a phone log and a calendar. They strip the emotion out long enough for you to see a schedule.
1. They call only when a bill is due
Eleven weeks, three requests, one phone call that had nothing to do with money. That was the tally when one woman finally wrote the dates down.
It had not felt strange from the inside, because her sister is warm on the phone. They laugh, they catch up on the kids, and somewhere near the end comes the part about the car registration or the light bill that arrived higher this month. The friendliness was real. So was the timing, and the timing was the thing she had been missing while she enjoyed the conversation.
Contact that clusters around rent, a repair estimate, a shutoff notice, while ordinary check-ins go quiet in the same weeks, is how a relationship narrows into a transaction. It rarely announces itself that way.
Keep a simple record for three months: the date of each call or text, and what it was about. If contact reliably comes just before a bill, you have your answer in your own handwriting, and it is a pattern rather than a suspicion. One emergency produces one such call. Several needs producing the same call is the role being assigned.
💡 Tip: Put a recurring reminder in your phone to review this log the first Sunday of each month. Patterns hide in memory.
A Loan or an Open Line
A real loan
- A repayment date is offered before you ask
- Partial payments arrive without a reminder
- You hear about a missed month before it happens
- The next request waits until this one is settled
An open line
- The amount is set by you, not by them
- The only follow-up is a new reason to wait
- Other creditors get paid first and on time
- Each cleared loan makes room for a bigger one
2. Emergencies arrive already solved by your transfer
There is a reason the timing question comes first: once you notice that contact rises and falls with need, the next thing to look at is how the request itself is built. Some arrive as a problem to talk through. Others arrive complete, with the transfer already assumed.
The shape of that message is specific. A sum, a deadline, and the account digits, all in one breath. "Car needs $600 by Friday, here's where to send it." What is missing is the part where anyone asks whether you can, whether the money exists this month, whether Friday works for you. The question has been answered on your behalf.
The misread is common. It feels like trust — you are the person they know will come through. But trust would still leave room for your answer. What this version signals is that you have been counted as available funds, not as an adult with a budget, an opinion, or a calendar.
A request built like an instruction has already decided what you are for. Notice that before you notice the amount.
🧭 The One-Boundary Test
Pick your least-arguable sign
Choose the behavior you could show someone on paper — a date, a message, a repeated amount.
Set one boundary, small enough to keep
Not "no more money ever," but "I won't answer same day" or "I don't discuss this after 9pm."
Script the first sentence
Write it down and say it out loud once, in the words you'll actually use.
Say it exactly once
No justification, no offer to discuss, no pre-apology attached to the end of it.
Note what happens next
Write down the response in the same log — the reaction tells you which behavior was being fed.
3. They quote a number before asking how you are
The small loss here is the greeting. A message that opens "Can you send $450?" and reaches "how are you doing" afterward, or never, has told you the order of its priorities, and the order can cost more than the money.
Once an emergency has been framed as an instruction, the sequence of the conversation becomes the telling detail. Researchers who study how people make and refuse requests keep landing on the same observation: the opening move sets the frame. Lead with context and the other person is invited to weigh it. Lead with a figure and the weighing has already happened somewhere else.
The two versions are easy to compare. "Hours got cut and the electric bill is due, can we talk about it?" leaves a door open. "Can you send $450?" treats your yes as a formality and your no as the interruption. One is a request. The other is a script with your line already written.
The caution is that a single blunt text proves little. Panic looks exactly like rudeness, and a person typing fast at a kitchen table with a shutoff notice in front of them may simply skip the pleasantries. One number-first message is a data point about that day, not about the relationship.
The sign lives in the repetition. If most asks over several months open with a figure, the order has stopped being incidental. It has been rehearsed, and rehearsal means the response has been counted on rather than genuinely asked for.
So before you read anything into the amount, read the first line of the last four requests. Whether a greeting ever came first tells you more than the number did.
⚠️ COMMON MISTAKE
Don't answer the number, answer the question
Replying with a smaller amount you can afford keeps the transaction alive and teaches the family that figures are negotiable. Reply to the framing, not the dollar figure: ask what the plan is, or say you need a day to check your own budget.
What the Family Assumes
This is the quieter layer. Nobody says "your money is our money" out loud, but the assumptions leak through in how relatives plan, what they know about your finances, and how they react when you decline.
These signs are harder to document than the first three. They live in language, in what gets asked and never asked, and in the temperature of the room after a no.
4. Your money is treated as household income
"We can afford it" is the sentence to listen for, because of the three words in it that are not yours. It arrives in a group chat about a cousin's wedding, or on a Sunday call about a shared purchase, and the arithmetic behind it includes your income and excludes your rent, your savings goal, and the card you are still paying down. The trip becomes possible because of what you earn, and nobody at the table asks what that income is already committed to.
"You have the most room" and "that's what family does" work the same way. Each one shifts the question from whether you want to help to whether you could possibly refuse, and the reader's own obligations quietly drop out of the family's planning. Help that is chosen leaves the reader a decision. Help that is expected has already decided for them, and the difference is not in the amount.
The larger the gap between what relatives assume is spare and what is actually spare, the more the next request will feel like an insult to say no to. That gap is worth naming out loud.
5. They know your salary but not your rent
Relatives tend to track raises and bonuses and to stop tracking everything that eats them. Ask what a relative thinks your rent is and the answer is often a guess, sometimes a generous one, and the request built on it uses gross income rather than the cash that actually reaches the end of the month.
A relative who knows about a 5,000 dollar bonus and nothing about the 1,900 dollar rent and 600 dollar childcare arriving the same month is working from an income figure, not a budget. The reader looks flush; the account says otherwise. One question settles it: has anyone in the family ever asked what your month costs before asking what you can spare?
6. Your no is heard as betrayal, not an answer
The common advice is to accept that a no will hurt feelings, because disappointment is the fair price of a boundary. That holds right up until the no lands and the cost runs higher than a hurt feeling. Then the phone goes quiet for two weeks, or a sibling calls to explain what your refusal did to your mother, or a favor from 2019 gets raised in a voice that expects repayment. A boundary usually isn't answered as a limit on money. It gets handled as a defection.
A relative who is simply disappointed says so and moves on. The one who punishes you, by withdrawing warmth, shaming you, or recruiting other relatives to argue the case, is showing what the answer meant to them: not information about your limits, but a toxic family pattern they refuse to break. The family was working from your income alone, so a no reads as a personal cut rather than an accurate report from inside your budget.
Say the decision once, then stop arguing about whether you were allowed to make it. Every round you spend defending the guilt reinforces the idea that your no needed justification. Back and forth about the feeling just keeps the role going.
7. They ask you to hide loans from relatives
The transfer clears, and then the second message arrives: "don't mention this to Mom." No reason attached, no harm named, just the instruction to keep a $700 loan out of the one conversation where your mother might ask what it was for. A refusal said out loud gets punished, so the ask moves into the dark where no one else can weigh in.
Privacy around money is ordinary. Plenty of people keep a loan between two adults and think nothing of it, and that is not the problem. The tell is secrecy trained on the transfer itself, the specific instruction that this particular help stay hidden from the relatives whose opinion would otherwise count.
A request kept quiet cannot be tested. Your aunt never gets to ask whether it was really needed, your mother never gets to say this is the third time, and the accountability that would slow the pattern goes with them. What you get instead is a private arrangement with one other person who needs it to stay private.
The Bank Role in Four Numbers
The figures that make the pattern visible
How You Get Pulled In
The final stretch turns inward. Some of these signs are behaviors the family runs; a few are habits you have quietly built in response, and those are worth looking at without flinching.
Getting pulled in is not stupidity. It happens because each individual request is small enough to absorb, and the sum of them is never visible from inside the moment.
8. You hear about their finances only at shortfall
For a long time the version of this I got wrong was thinking I was being trusted with the important stuff. A cousin calls, the account is short, the story arrives complete and urgent, and I was flattered to be the one told. It took a while to notice I was never told anything else.
The savings, the spending, the plan for next month, none of it ever came up. There was no update in a good week, no mention of a budget being built, no word about the raise or the side work. The first anyone heard about the finances was the moment they fell short, and the conversation ran from the deficit straight to the ask.
That is what selective disclosure looks like from the inside. You get the crisis and never the picture, so you are answering an emergency instead of a question. The loop is predictable: it starts with a hole in the account and ends with a transfer, and you have no way to tell real need from a gap that will open again next month.
The move is to ask for the picture rather than promise the money. "What is the plan before the next shortfall?" is a request for the budget, not a pledge to cover it. It also tells you something. Someone with a plan will describe it, roughly, even badly. Someone who only ever has emergencies will change the subject or get hurt that you asked.
You cannot tell whether you are funding a bad month or an ongoing habit if you only ever see the hole. Ask, once, what the month looks like from the beginning, and let the answer decide what you do at the next deficit.
9. Small requests grow after you pay without complaint
What gets rewarded gets repeated, and the payment you made without a word was the reward.
It starts small enough to be nothing. Twenty for gas, then a phone bill that is suddenly $120, then a month where the rent is short by $900 and the request arrives with the same casual tone as the gas money did. The amount changed; the ease of asking did not, because every smooth payment taught the family that a bigger number would meet the same quiet yes.
The mechanism is not mysterious and does not need a lab. A request that works gets tried again, and one that works without friction gets tried at a larger size. If you pay to keep the peace, the peace is what you are buying, and the price is set by whoever keeps asking.
One larger request proves nothing on its own; people have bad months. The pattern is tested across several asks, and it is the run of them, each a little heavier than the last and each met with the same complaint-free transfer, that tells you what you are in.
💡 Tip: If you notice a request climbed by a third since last year, that is your cue to slow the answer, not match the figure.
💡 PRO TIP
The day-of-reply delay
Make it a standing rule that you never send money in the same conversation where it was asked for. That single pause breaks the automatic quality of the transfer and gives you realistic ground to answer from.
10. They repay others first because you can wait
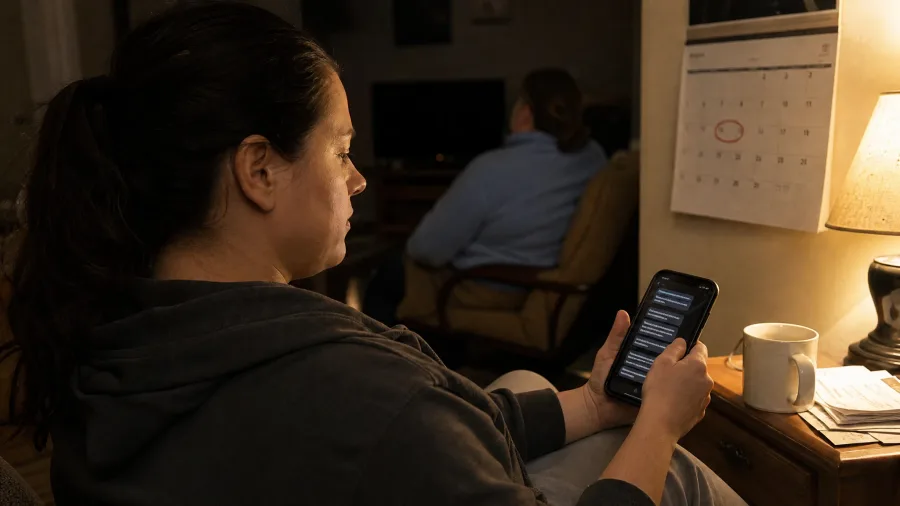
Six months is how long a $500 loan can stay open when the person who owes it knows you will not knock. Meanwhile the landlord gets paid on the first, on time, every month. The bank gets its payment. A louder cousin gets hers before the week ends. Your name sits at the bottom of the list, and the order is not about cash flow.
The obvious advice is to be patient, to be the bigger person, to trust that family sorts itself out. That advice is wrong here, because the ranking is the message. Repaying the insistent ones first and you last tells you plainly what your patience has been priced at: an endless credit line, one that never comes due because you never make it come due.
Watch what arrives instead of the money. A date and a partial payment are a plan. 'Next month, I promise' followed by a new reason every month is not a plan, it is a stall dressed as one. If you have helped steadily and the amounts kept climbing while your place in the repayment order kept sinking, the pattern runs in one direction.
The test is small. When the next excuse lands, ask once for a date and an amount, in writing, and see what comes back. A person who values the loan gives you both. A person who values your willingness to wait gives you another month and another story, and that answer tells you where you actually stand with your money.
11. You feel guilty before anyone asks for money
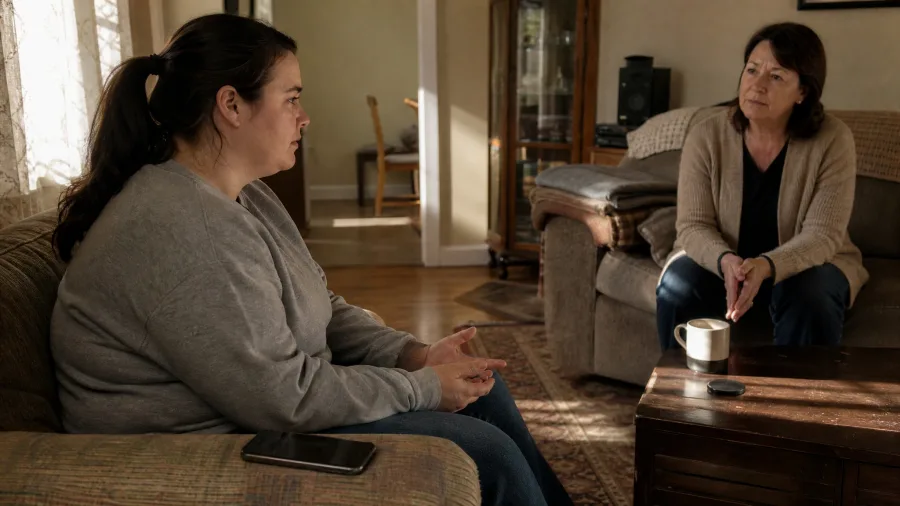
The version I got wrong: for a stretch I found myself checking my balance before a family dinner, not because anyone had asked for anything, but because the ask felt due. Nobody had mentioned money. I had already run the numbers, already half-spent the transfer in my head, and already felt vaguely selfish for wanting to keep it. That is what being ranked last does over time. It turns the pattern inward, and you start bracing for a request that has not been made.
It shows up in small ways first. You rehearse the text before it arrives. You explain a purchase nobody asked about, listing the reasons a new jacket was necessary to a relative who never mentioned it. You look at your own savings and feel a flicker of guilt, as though the cushion under you were somehow taken from someone else. None of these are proof of anything except that the sequence has become predictable.
Repeated asks do train anticipation. That part is fair, and it is not a character flaw. But the feeling is not evidence of an obligation. Guilt that arrives before the request is your body running an old script, not a bill that has come due. The distinction matters because guilt is exactly the lever that makes a boundary feel impossible, and it operates best before there is anything to actually respond to.
this is the feeling, not the request. Then wait. Do not send the pre-emptive explanation, do not offer the money before it is asked for, do not soften a decision nobody has questioned; enjoying being alone with the silence is allowed. If a real request comes, you answer it as a request, with a budget and a yes or no. If none comes, you have just discovered that the guilt was doing all the work.
The feeling arriving early is the clearest sign that the bank role has moved inside. The external pattern has become an expected event, rehearsed on your side before anyone acts. That is worth knowing, because it means the next ask is not the hard part. The hard part is the quiet evening before it, when you notice the dread, let it sit, and reply to nothing at all.
A no that sounds like betrayal isn't proof your no was wrong. It's proof the answer was expected to be yes.
— What people on the receiving end of family asks keep landing on
Frequently Asked Questions
Is the whole family doing this on purpose?
Usually not. Most of it is an accumulated expectation rather than a plan, and the people asking would often be surprised to hear it described as a pattern. That is why naming one specific behavior out loud is more useful than accusing anyone of a motive.
What if this really is a one-off emergency?
Then it will behave like one. A genuine emergency tends to arrive with context, an apology for the timing, and some offer of a plan. The sign of the bank role is repetition across several needs, not a single hard month.
Should I stop lending entirely?
Not necessarily, and the article does not ask you to. The point is to change one variable — the timing of a reply, the secrecy, the automatic yes — so you can see what happens when the pattern is interrupted.
What do I say when they bring up everything they have done for me?
You do not weigh the ledger out loud. "I'm not taking anything away from that. I still can't do this one" keeps the answer intact without arguing about the past.
How do I cope with the guilt after a no?
Expect it and let it sit. Guilt after a no is a normal response to breaking a habit that went unspoken for years. You are not required to resolve the feeling before you hold the decision.
Run One Low-Heat Money Experiment
You do not need to decide what your family is today. You need one low-heat experiment. Pick the sign in this list that is least arguable — the dated call log, the message that opens with a figure, the loan that is now four months late — and choose one boundary small enough that you can genuinely keep it.
Write the first sentence you will say when that behavior happens again, and say it once. What returns afterward, whether it is a question, a plan, or a cold silence, is the information you were missing. That is the whole test.
Read your three-month log next Sunday. Then say the sentence, and let the conversation be whatever it turns out to be.
Open your bank app tonight
Filter the last three months of outgoing transfers to family. The number you see and the number of calls that preceded them is your starting point for the one-boundary test above.